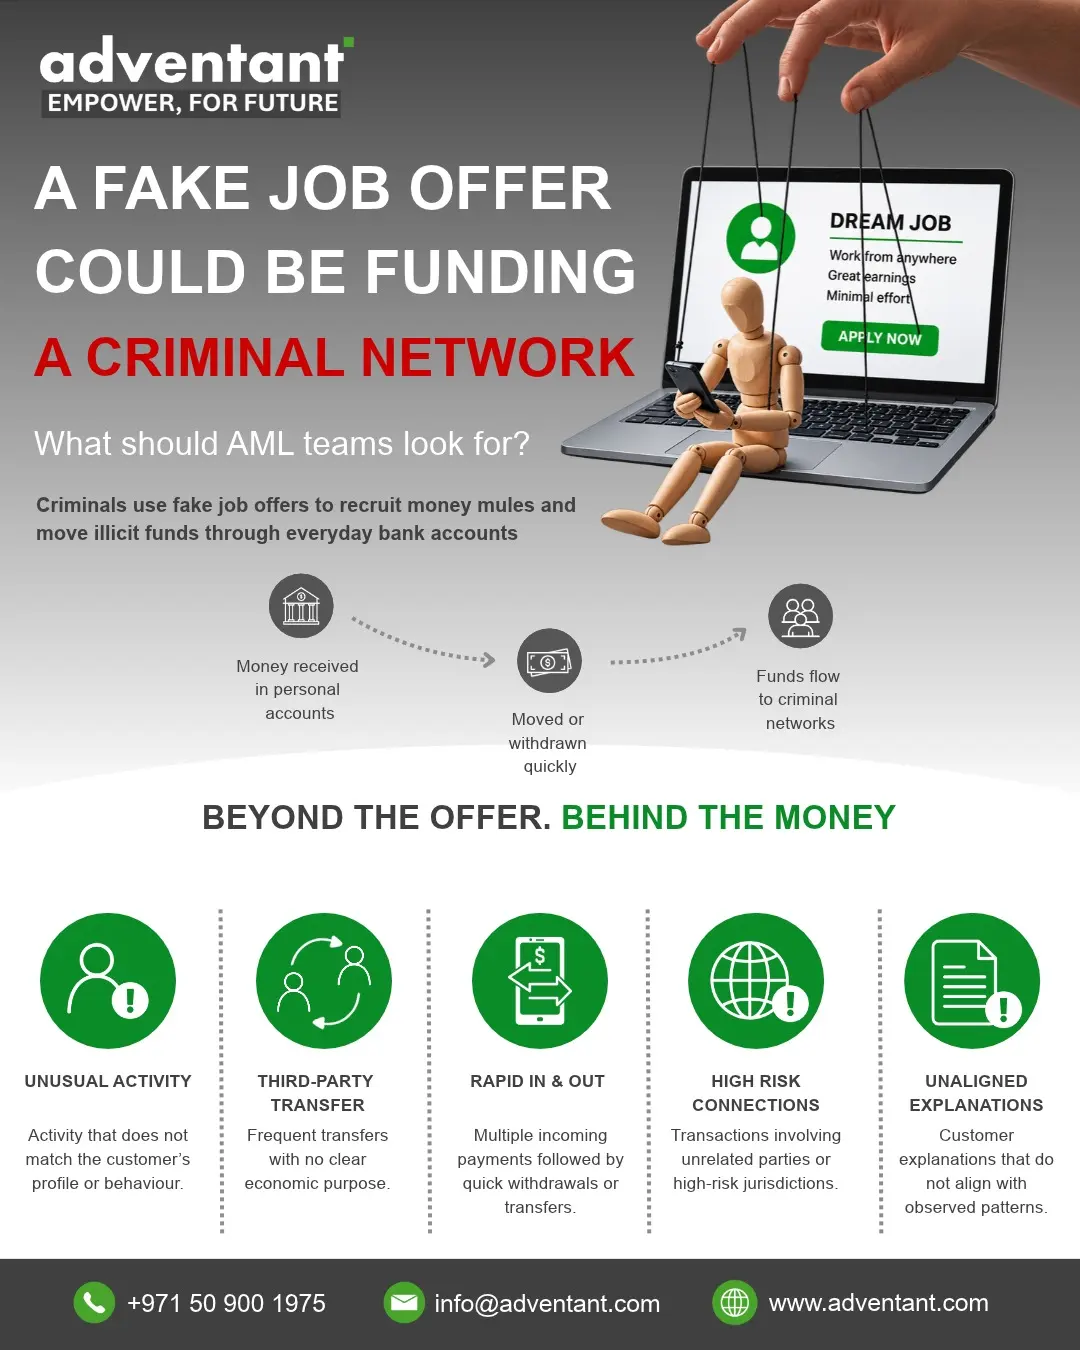
A fake job offer could be funding a criminal network
Criminal networks use fake job offers, often promising remote work, high pay and little effort, to recruit money mules. These are people persuaded to receive illicit funds into their personal bank accounts and then withdraw or transfer them on. The money looks like ordinary activity on an ordinary account. AML teams should watch for activity that does not fit the customer's profile, frequent transfers from unrelated third parties, money that arrives and leaves quickly, links to high-risk jurisdictions, and explanations that do not match what the account shows.
At a glance
- Fake job offers are used to recruit money mules, who move criminal funds through their own accounts.
- The typical pattern: money received into a personal account, moved or withdrawn quickly, then passed on to the criminal network.
- Five red flags: unusual activity, third-party transfers, rapid in and out, high-risk connections and explanations that do not fit.
- The red flag is not always the transaction. Sometimes it is how the person was recruited.
The detail, step by step
Understand how the recruitment works
The offer usually arrives through social media, messaging apps or job sites and promises remote work, high earnings and minimal effort. The "job" is described as payment processing, account management or acting as a local agent. In reality the person is being asked to lend their bank account to move money that is not theirs. Some recruits know what they are doing; many do not realise until their account is frozen.
Watch for activity that does not match the profile
Compare what the account is doing with what you know about the customer. A student, a newly arrived worker or a dormant account that suddenly receives and sends large or frequent payments is the clearest early warning.
- Unusual activity inconsistent with the customer's profile or past behaviour.
- Turnover far above the customer's declared income or occupation.
Look at who is paying and who is being paid
Mule accounts typically receive money from several unrelated people and pass it to others with no clear economic purpose. Look at the counterparties, not just the amounts.
- Frequent third-party transfers with no clear reason.
- Transactions involving unrelated individuals or high-risk jurisdictions.
Check how long the money stays
Money mules are paid to move funds quickly. Multiple incoming payments followed by rapid withdrawals, cash withdrawals or onward transfers, often within hours, is a classic pattern. Set monitoring rules for short holding periods, not only for large amounts.
Talk to the customer and test the explanation
When an alert fires, ask the customer what the payments are for. Explanations such as a new online job, helping a friend or processing payments for a company they have never met should be tested against the observed pattern. Be careful not to tip the customer off about any suspicion you may report.
Escalate and report
If the explanation does not hold, escalate to the MLRO or Compliance Officer, record the decision, and where there are grounds to suspect, file a suspicious transaction or activity report through goAML. Consider whether other accounts linked to the same counterparties are part of the same network.
Mistakes to avoid
- Monitoring only for large amounts, when mule activity is often many small or medium payments.
- Treating each payment in isolation instead of looking at the pattern across counterparties.
- Accepting "it is for my new job" without asking what the job is and who the employer is.
- Closing the account without considering a goAML report or links to other accounts.
Evidence to keep
- Alert records showing the pattern reviewed, not just the single transaction.
- Notes of the customer's explanation and how it was tested.
- The MLRO's decision to report or not report, with reasons.
- goAML submission references where a report was filed.
Questions answered
What is a money mule?
A money mule is a person who receives money into their own bank account and moves it on, by transfer or cash withdrawal, on behalf of someone else. The money usually comes from crime, and the mule may or may not realise it.
How do criminals recruit money mules through job offers?
They advertise roles that promise remote work, high pay and little effort, often described as payment processing or acting as a local agent. The real task is to let the recruit's bank account be used to move criminal funds.
What are the main red flags of money mule activity?
Activity that does not fit the customer's profile, frequent transfers from unrelated third parties, money that arrives and leaves quickly, links to high-risk jurisdictions, and explanations that do not match the transactions.
What should an AML team do if it suspects a money mule account?
Review the pattern across the account, test the customer's explanation without tipping them off, escalate to the compliance officer and, where there are grounds to suspect, file a suspicious transaction report through goAML.
Where Adventant can help
General information only, not legal or compliance advice. The examples and figures are invented for illustration. Your obligations depend on your activities and your regulator, so check the current rules that apply to you or speak to Adventant about your situation.